ServicesMotor Truck Cargo Insurance
Motor Truck Cargo Insurance in Grand Prairie
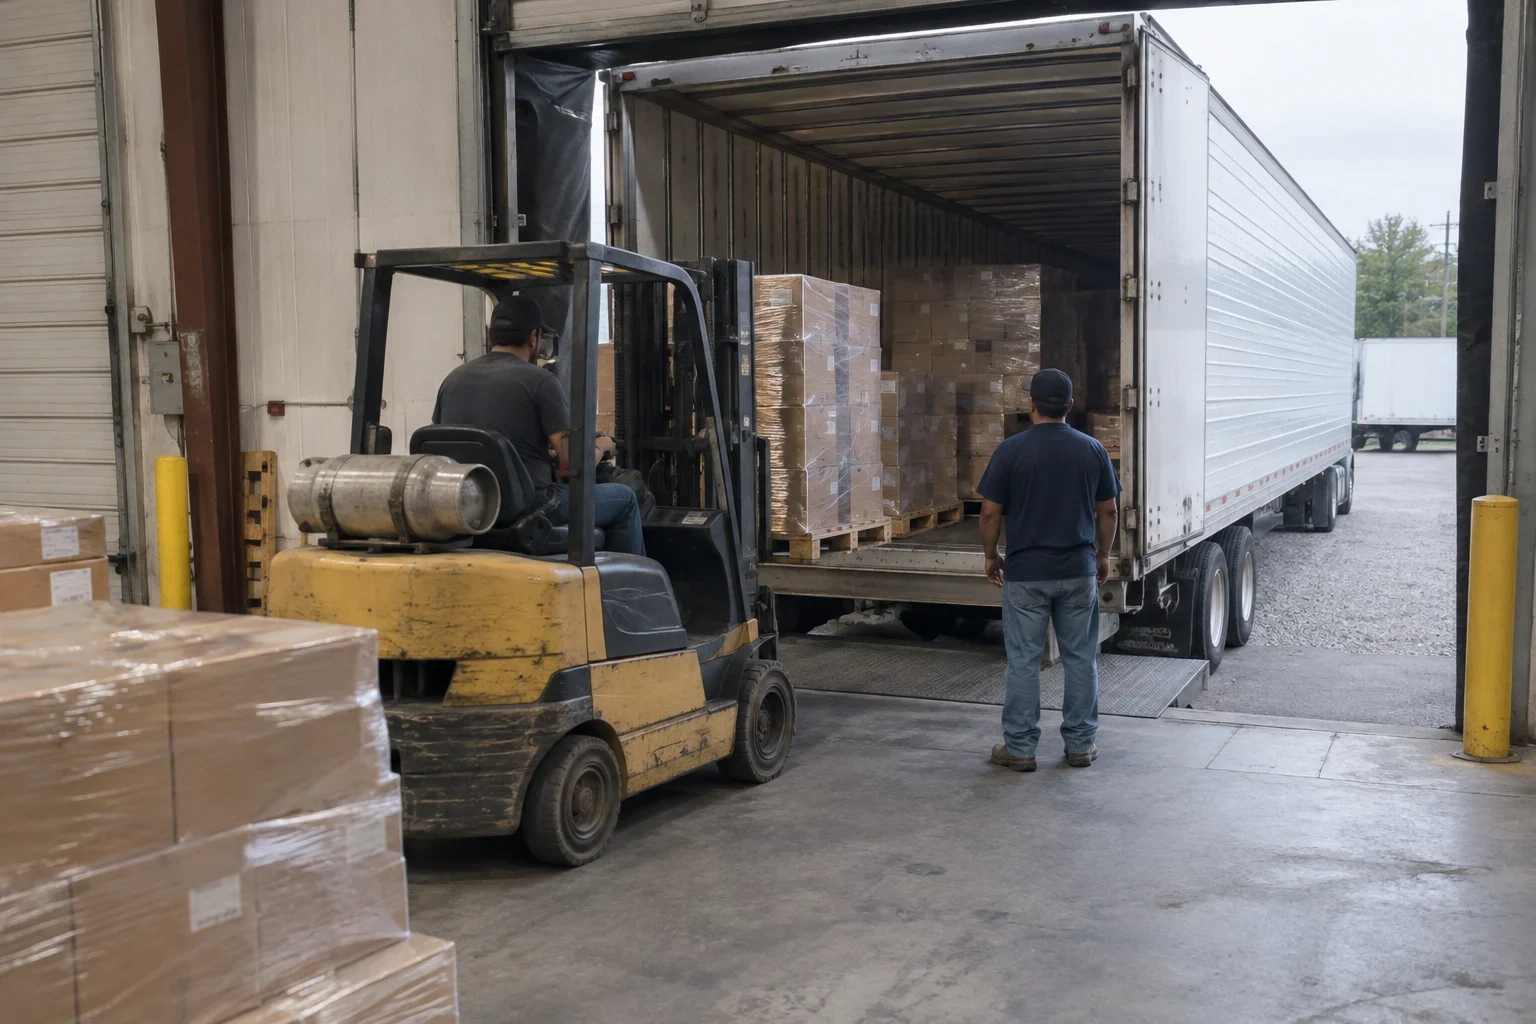
Motor truck cargo insurance pays for the freight on your trailer when it is stolen, burned, wrecked or spoiled. We match the policy to your commodities and your broker contracts, then show you the exact policy pages that decide whether a claim gets paid.
What cargo coverage does and where it falls short
Your auto liability policy covers damage you do to other people. It does not cover the load behind you. Motor truck cargo insurance fills that gap, paying the shipper or broker for freight lost or damaged while it is in your care, custody and control.
The problem is that cargo forms vary more than almost any other trucking policy. One form excludes theft from an unattended trailer. Another drops coverage for reefer breakdown unless you bought an endorsement. Many list commodities they will not cover at all, such as electronics, tobacco or alcohol. A policy can look fine on the certificate of insurance and still deny the one claim you are most likely to have.
So we read the form, not just the declarations page. When we review your coverage, we mark up the exclusions and conditions that matter for your freight and send you copies, so you can see what we found and what we changed.
What we review and set up
Commodity list check
We compare what you actually haul against the policy's covered and excluded commodities. If you run building materials Monday and packaged food Thursday, both need to be on the schedule.
Limit matched to the contract
Brokers write a cargo limit into the broker-carrier agreement. We set your per-load limit to meet it, and flag loads whose value could exceed it.
Reefer breakdown endorsement
Temperature-controlled freight needs specific wording for spoilage caused by a refrigeration unit failure. Without it, a dead compressor can leave you paying for a full load of produce yourself.
Theft and unattended vehicle terms
We read the conditions on parking, locks and how long a trailer can sit unattended. These clauses deny more theft claims than anything else in a cargo form.
Certificates for brokers and shippers
We issue certificates of insurance with the cargo limit and deductible shown clearly, and add certificate holders when a new broker asks.
Signs your cargo coverage needs a second look
A broker rejected your certificate
Usually the limit is too low, the deductible is too high, or a commodity exclusion conflicts with their freight. All three are fixable before you lose the lane.
Your freight mix changed
Moving from dry van general freight into reefer, machinery or high-value goods often falls outside the original commodity list.
You have never read the exclusions
If your only copy is a one-page certificate, you have not seen the form that governs claims. Ask for the full policy.
You park loaded trailers overnight
Drop yards and truck stops along I-20 and I-30 see trailer theft. Your policy's unattended vehicle clause decides whether that loss is covered.
A past claim was reduced or denied
A partial payment usually points to a specific condition, such as a missing reefer download or an unlisted commodity. We find the clause so it does not happen twice.
How a cargo quote works with us
- 1
Phone or video call
We ask what you haul, your typical load values, trailer types, and which brokers or shippers you work with. Have your DOT number and MC authority handy.
- 2
Policy and contract review
If you have a current policy, send us the full form. We pull the exclusions, conditions and endorsements and mark them up so you can see each issue on the page.
- 3
Quotes compared line by line
We lay out each carrier's limit, deductible, reefer wording, theft conditions and commodity list side by side, so the cheapest premium is not hiding a gap.
- 4
Binding and certificates
Once you choose, we bind coverage and send certificates of insurance to the brokers on your list. You get a copy of everything we sent.
What moves your cargo premium
Cargo premiums are priced on the risk of the freight more than the truck. Two operators with identical tractors can pay very different premiums because of what sits behind them. These are the factors underwriters weigh most.
- Commodities hauled
- Theft-prone and perishable freight costs more to cover than lumber or aggregate. Electronics, meat and pharmaceuticals sit at the top.
- Limit and deductible
- A higher per-load limit raises the premium. A higher deductible lowers it, but some brokers cap the deductible they will accept.
- Reefer and theft endorsements
- Adding reefer breakdown coverage or broader theft wording increases cost, and is often worth it for the freight it protects.
- Loss history and authority age
- Prior cargo claims and a new MC authority both raise rates. Clean years with the same authority bring them down.
Motor truck cargo insurance questions
Something not covered here? (972) 236-7691
Is cargo insurance required by the FMCSA?
For most general freight carriers, federal rules do not require a cargo filing. In practice, almost every broker and shipper requires it in their contract, so running without it limits the loads you can book.
How much cargo limit do I need?
Start with the limit written in your broker-carrier agreements, then look at your highest-value typical load. Your limit should cover both. We check your contracts during the call so the number is based on your freight, not a guess.
Does cargo insurance cover spoiled reefer loads?
Only if the policy includes reefer breakdown coverage, and usually only when the unit failed mechanically. Many forms also require temperature download records after a loss, so keep the reefer's data logs.
Will photos help if I have a claim?
Yes. Photos of the load at pickup, seal numbers and the trailer at delivery give the adjuster a clear record of condition. We encourage clients to take them on every load, and we include them when we help report a claim.
Can I add cargo coverage to my existing policy?
Often it can be written with the same carrier as your primary auto liability or physical damage coverage, or placed separately. We compare both ways and show you which forms fit your freight better.
See what your cargo policy actually covers
Have your current policy and broker contracts nearby. We will walk through the exclusions with you and quote coverage that fits your freight.